|
|
|
Where we are starting
Welcome to the first one of these. Here is what you are getting, so you can decide right now whether to stay subscribed. I write about three things and nothing else. People who work nights and weekends and holidays, and the veterans among them, because I lived that life. My family and this town, because I am standing in the same grocery store line you are. And mortgages explained in plain English, because most of what gets explained to buyers is not explained at all. It is just said faster.
| |
|
Same town, same week
My oldest left for college a few weeks ago. I have moved a lot of people into a lot of houses. I did not expect a dorm room with a shared bathroom to land on me the way it did. You do the drive home and the car is quieter than it has any right to be. If you are doing the same thing this month, you are not imagining how strange it feels. Half this town is doing it at once and almost nobody says it out loud. I bring it up because it is the same feeling I watch cross my desk all year. Anybody who tells you a house purchase is a spreadsheet has not sat with a family at a closing table.
| |
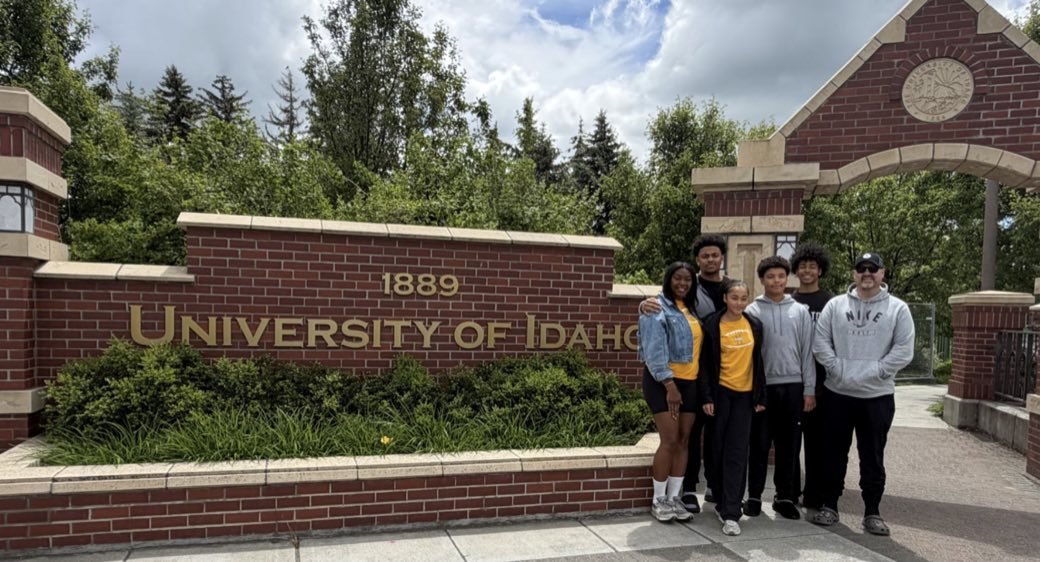
The drop-off, before the drive home.
| |
|
Eight months on the job
A while back I got talking with a young firefighter. Now eight months on the job. He told me he figured he was about five years out from buying anything. Not because anyone had run his numbers. Because he had heard you need twenty percent down. Because half of his income comes from overtime and shift differential, which is the extra you get paid for working the hours nobody else wants, and he assumed no lender would count a dollar of it. And honestly, because he did not want to ask and get told no in front of people he works with.
| |
|
What is actually on my desk this month
A seller credit is money the seller agrees, at closing, to put toward the buyer's costs instead of keeping. It gets written into the offer. It is a normal, ordinary part of a normal, ordinary deal. Most first time buyers have never heard the phrase, so they never ask for it, so they never get it. Here is the part that is not obvious. A house that has been sitting on the market for ninety days is a completely different conversation from a house that went up on Tuesday. That seller has already had ninety days of nothing. At that point an offer that is clean and certain, with a credit attached, often beats a higher offer that is slow and shaky. Price is only one of the things a seller is counting. This is also where I do something a lot of loan officers do not do. When my client makes an offer, I do not only speak to my client's agent. I call the agent on the other side. I tell them who my buyer is, where the pre-approval stands, and how fast we can get to closing. That is the financing, and the financing is my part of it. The credit itself is negotiated between the two agents, not by me. What I can do is make sure it is on the table and that everybody knows the file can carry it. Plenty of sellers say no. A lot of them say yes. Nobody in five years has been offended that it came up. What that credit is best used for, the costs of closing or the cost of the financing itself, depends entirely on the file in front of me. That part is a conversation, not a rule.
| |
| |
|
Back to the firefighter
He did not leave that conversation with a house. He left with a list. The paperwork that puts his overtime on the record instead of in his memory. A real look at what he could be shopping for now rather than in five years, and what would make that number better between now and then. And the knowledge that asking a seller for a credit is a standard move, not a favor he would owe somebody for. He was not five years out. He was never five years out.
| |
|
Somebody else's words
I am not going to sit here and tell you I am good at this. Here is a note from a couple who just closed on their first house.
The line I want you to notice is the hectic work schedule one. Working around somebody's hours is not a favor I do. It is the whole job. | |
| |
|
That is the first one. If there is a question you have been too embarrassed to ask a lender, hit reply and send it to me. I will answer it in a future issue. No names, ever. Thad | |
|
|
First responders and veterans. Family and community. Mortgages in plain English.
That’s all I write about.
Your Mortgage First Responder
Thad Kerkhoff · Loan Officer, NMLS ID# 2180739 CMG Home Loans · NMLS ID# 1820 206.604.4447 · tkerkhoff@cmghomeloans.com |
|
Nothing in this email is a commitment to lend, and no rate, term or approval is offered or implied. All loans subject to underwriting approval. CMG Home Loans, 350 Madison Ave, N Suite 4, Bainbridge Island WA 98110 |